

BY: Bethany McLean
EDITORS: Vikas Kumar, Jim Impoco
Nvidia ($NVDA) no longer just sells chips. It invests in its customers, buys their computing capacity, and backstops their rent. Its commitments show how much the roughly $5 trillion company has riding on the AI boom.
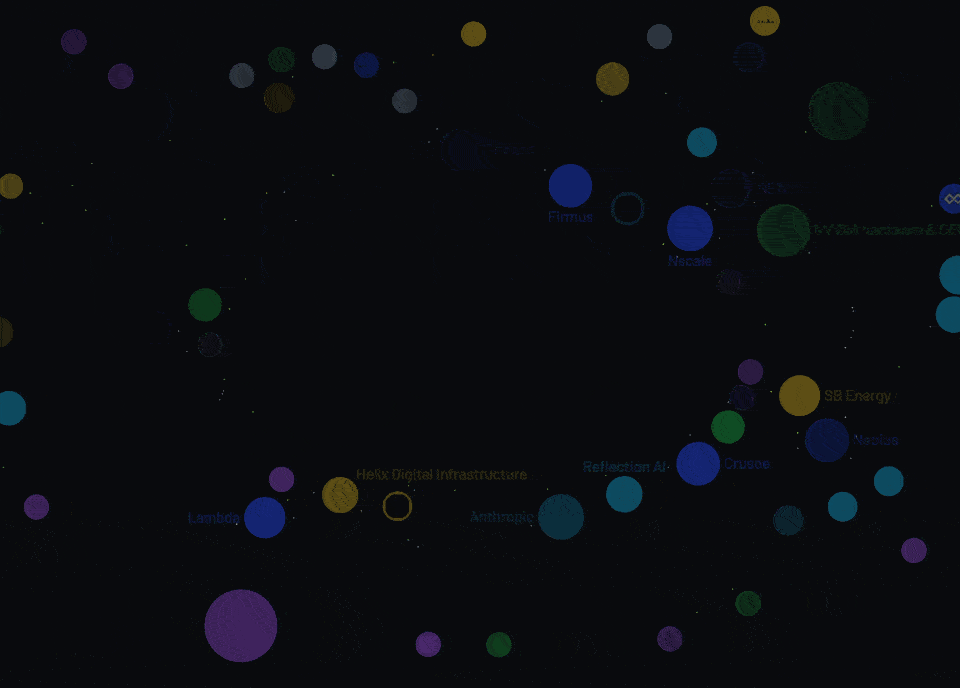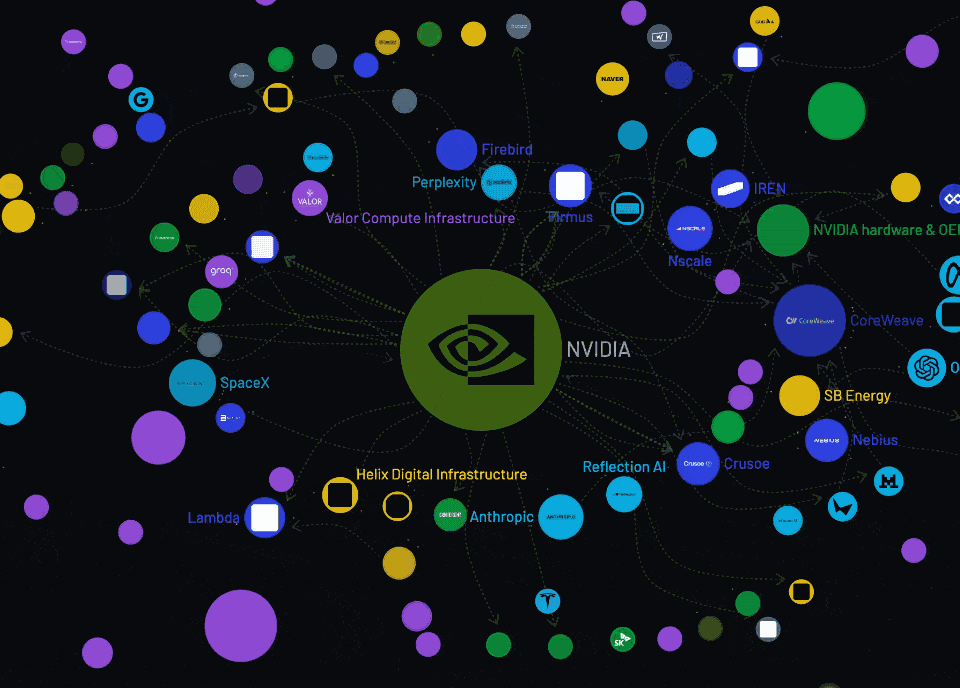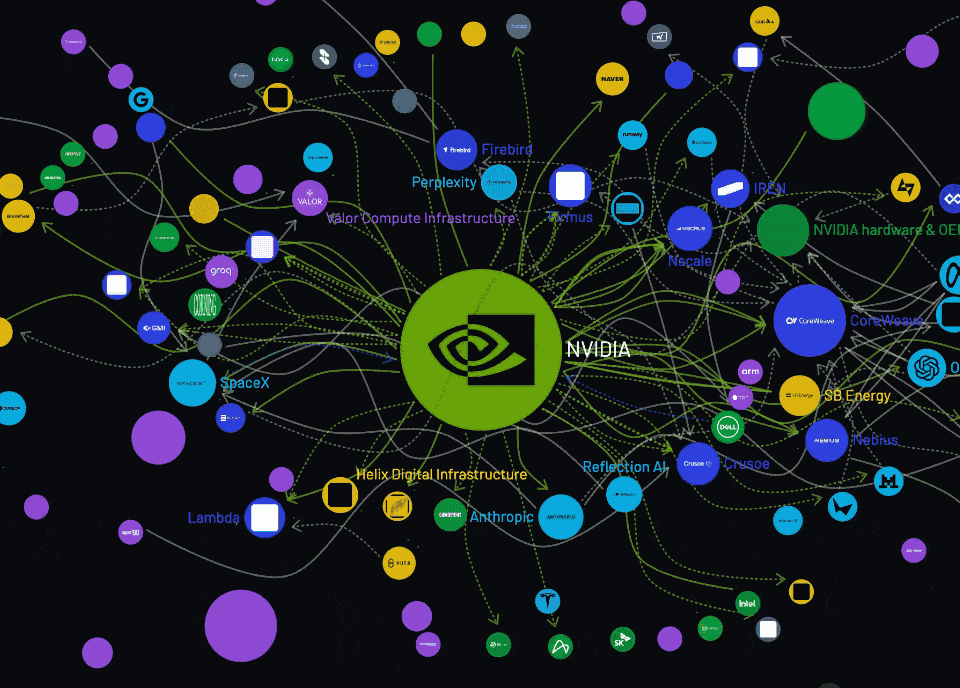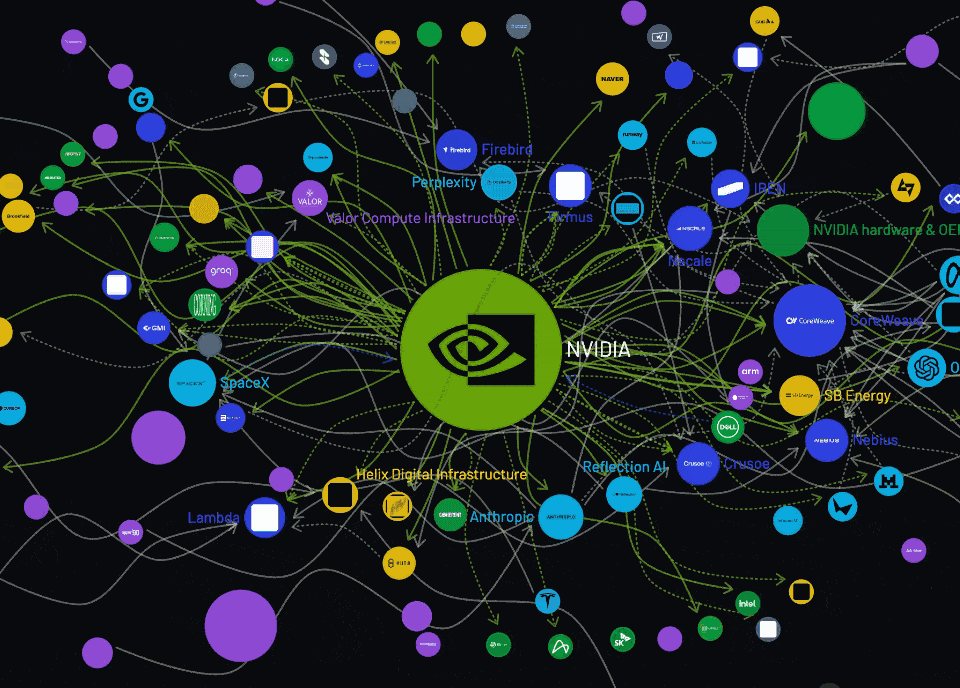
Every financial news publication has written about Nvidia’s round-tripping and backstopping. Hunterbrook decided to go a step further — tracing every dollar Nvidia has committed to its partners in one comprehensive place.
This will be a living document; and as new Nvidia financing agreements are announced, we will add them.
Because if Nvidia is really the central bank of AI, as the company’s backers say, then the world needs to know everything it is backstopping.
Hunterbrook Media’s investment affiliate, Hunterbrook Capital, does not have any positions related to this article at the time of publication. Positions may change at any time. Full disclosures on our website.
“We put a little bit of money in, and a lot of money comes back,” said Nvidia CEO Jensen Huang at a Goldman Sachs conference in mid-September. “I look at the spreadsheet, we put in $1 and $100 comes back. Is that circular? If that is, let’s do more of that.”
Nvidia is certainly doing more of that, and its circular machine is spinning ever faster. On a recent European tour to pitch national leaders on the necessity of “sovereign AI,” Huang played the part of Silicon Valley’s ultimate patron, announcing investments in startups in France and Britain. In Paris, clad in his trademark black leather jacket and holding a whiskey glass, he announced investments in four startups and quipped that he had become “the biggest VC in Europe.” In London, he worked the stage of a converted church like Oprah giving away cars: “I am giving you money! And I am giving you money! And I am giving you money!” he shouted.
He also said he would splash another $2 billion in investments in European AI within a week.
The idea, of course, is that all roads lead back to Nvidia. By putting this money out, Nvidia reckons it will get back magnitudes more both through direct purchases of its chips and indirect purchases when companies it backs rent computing capacity from other companies that also use Nvidia chips.
“You’ve effectively had to become the bank of AI to get the ecosystem going,” investor-podcaster (podcaster-investor?) Chamath Palihapitiya said to Huang at the All-In Summit in September.
This is not an act of selflessness on Nvidia’s part. As former Microsoft ($MSFT) executive and angel investor Charles Fitzgerald points out, technology companies in Nvidia’s position have a choice. They can either sit back and return the gusher of profits to shareholders — or try to lock in their dominance. “They have the wonderful problem of, ok, lightning has struck,” says Fitzgerald, who runs the strategy consulting firm Platformonomics. “They were in the right place and the right time. They have chosen to invest for long term dominance.” It’s similar to what Microsoft did by locking in corporate America’s dependence on Windows, and as Fitzgerald notes, it may not be a coincidence that Nvidia’s CFO is ex-Microsoft. “Constitutionally, as a tech company, you have to double down when you have these opportunities,” he says.
Transforming itself into the primary hub of the circular AI economy has helped make Nvidia the first public company in history to crack the $5 trillion threshold. But there is also substantial risk, especially if weaker players in the ecosystem start to wobble.
In theory, any losses Nvidia suffers as a result of its investments in companies like CoreWeave ($CRWV) should be manageable. But when investor confidence cracks, as it did in the 2008 subprime crisis, the circular economy can turn into a circular firing squad, with losses rippling in ways that are impossible to see until it happens. Another danger is if the competitive landscape shifts as alternatives like Google’s TPU chips and Amazon’s Trainium chips begin to make inroads, while a greater share of compute is devoted to inference that can be handled by the CPU chips rather than the GPU chips that are Nvidia’s core differentiator.
An oversupply of compute would present yet another risk. Nate Koppikar, who runs Orso Partners, and senior analyst Ryan Greener have done a bottom-up analysis and estimate that by the end of 2028, there will be 17 gigawatts of excess supply of compute.
The results of the election also add another wrinkle. Nvidia itself has warned that one risk is that “customers may postpone purchasing new architectures due to the lack of availability of data center infrastructure.” In Texas, voters just elected a governor who ran on her opposition to the unchecked expansion of data centers.
Others have written about aspects of Nvidia’s round-trip capital commitments, but Hunterbrook Media wanted to find out the full extent of what the company has agreed to support. So we combed through Nvidia’s financial statements and its announced deals to calculate its total commitments and identify the connections between the companies in its financing loop.
The Information recently reported that Nvidia has put $170 billion on the line to support neoclouds. But we found that the company’s overall committed capital extends much further. Tallying the disclosures in Nvidia’s latest 10-Q reveals a whopping $530.5 billion in future commitments and guarantees.
The obligations span several buckets: supply commitments, equity injections into neoclouds, backstop guarantees for data centers, and agreements to purchase unused capacity from partners.
The $530.5 billion figure doesn’t include deals that post-date the 10-Q, like the preliminary agreement Nvidia just reached to inject $100 billion of equity in 10 installments into OpenAI, each one tied to OpenAI placing orders for Nvidia chips, or any of those European deals.
Taken together, the numbers show how much Nvidia is putting on the line to keep the flywheel turning. “Is Nvidia now the central bank and lender of last resort?” asked the longtime investor Doug Kass of Seabreeze Partners Management in a recent column. “Is the Federal Reserve’s Kevin Warsh the boss, or is it now Nvidia’s Jensen Huang?”
Perhaps the bigger question, to switch the metaphor, is what will happen if the arsonist feeding the flames also has to put out the fire?
THE COMMITMENTS BEHIND THE BOOM
“Circularity” — the idea that Nvidia invests money in a company that then buys its chips — doesn’t do justice to the reality. The company is making advance commitments for parts it needs so that it can secure supply. It is signing leases on data centers for its own work and also guaranteeing the leases on data centers for other companies in the event they can’t pay. It invests in neoclouds that buy its GPUs, yes, but may also have money in the customers of these neoclouds, like frontier labs Anthropic and OpenAI.
It’s one thing to grease the skids. It’s another thing if companies and data centers and investment coalitions that wouldn’t otherwise get financed do so only because of Nvidia’s involvement. In other words, the company could be increasing the risk in the overall system. And if the cracks continue to grow, the worry is that not even Nvidia’s dollars would be able to paper them over.
Nvidia has started to disclose more of its commitments, in part to address investors’ worries about the scale of its exposure. And the way Nvidia thinks about its own numbers is revealing. The baseline category, which it labels “future commitments,” stood at $366 billion as of July 26. The figure’s largest component is $279 billion in advance purchase orders and pledges to various suppliers of memory and of the packaging, testing, substrate and optical components Nvidia needs for its systems. Nvidia’s CFO said at the end of the first quarter that high bandwidth memory chips the company depends on primarily accounted for the surge.
This line item is getting bigger fast — the $279 billion was up from just $119 billion three months earlier, which is an increase of $160 billion or 134%.
Since the end of the second quarter, it has gotten even bigger. On October 21, Nvidia announced an expansion of its commitments with six suppliers. A big one is Siliconware Precision Industries, a Taiwanese semiconductor packaging and testing company. Nvidia said SPIL aims to increase capacity for optical engines used in co-packaged optics 15-fold by mid-2027. Nvidia didn’t put a dollar amount on the commitment.
Theoretically, locking in supply before others do is an advantage. Throughout 2025 and 2026, Huang himself criscrossed Asia, securing deals. Bulls see this as one of the smartest things that Nvidia has done. One reason Google’s competing TPUs may not have scaled as quickly is because of supply shortages.
Nvidia doesn’t name its suppliers or disclose deal-by-deal terms. It says some agreements “may be cancelable, rescheduled, or adjustable” before firm orders are placed, but doesn’t say what share is firm. If demand for Nvidia’s chips doesn’t grow as it expects, then of course it loses the anticipated revenue, but may also find itself on the hook to pay its suppliers.
This is the financial trap fiber optic companies like Lucent and Nortel found themselves in after the dot-com bubble burst. They were each stuck with over $1 billion — which was real money back then — in charges for suppliers and inventory that the market no longer wanted. Compared to Nvidia’s current balance sheet commitments, those figures look positively quaint. In 2000, Cisco, which also had massive exposure to vendor financing, seemed to have everything under control. “They knew exactly what was going to happen — until they didn’t,” says Fitzgerald.
Cisco’s stock price only returned to its 2000 high last year, in December.
Another part of the $366 billion ledger is $29 billion in something called “cloud service agreements,” which is money Nvidia is committed to pay for internal research. In February, an Indian company called Yotta announced that it was hosting capacity for Nvidia’s DGX Cloud service in a four-year agreement that it said was worth more than $1 billion.
Yotta is simultaneously a major buyer of Nvidia’s chips. So in effect, Nvidia sells Yotta the equipment, and then becomes a customer for some of the cloud capacity that Yotta builds with it. Yotta says that Nvidia is expected to account for roughly half of the outtake, meaning that Yotta’s operating model is heavily dependent on its anchor vendor, Nvidia.
Another $25 billion of the $366 billion is for leases that Nvidia has on data centers for its internal engineering facilities. Nvidia doesn’t name the sites or landlords. There’s also $25 billion in pending equity commitments, a portion of which could reflect Nvidia’s $30 billion investment in OpenAI, which has not been completely funded yet.
The last tranche of the $366 billion is another $8 billion in capital expenditures, mainly for data-center infrastructure and testing equipment for internal operations. The filing doesn’t name a specific project.
THE CIRCLE GAME
Beyond that $366 billion, Nvidia reported another $56 billion that it labeled “additional commitments.” This one consists of $36 billion in AI-cloud agreements (in which Nvidia commits to buy cloud capacity from neoclouds that bought its hardware; the neoclouds can pull that capacity back and sell it to other customers, which shrinks Nvidia’s obligation) and $20 billion in data-center leases that have not yet begun and which Nvidia plans to reassign to third parties. The second quarter was the first in which Nvidia’s 10-Q broke all these figures out into a dedicated reporting category, so the historical run rate can’t be tracked.
CoreWeave illustrates how the mechanics work. In 2025, it disclosed a $6.3 billion order that obligates Nvidia to buy residual capacity CoreWeave can’t sell to other customers through April 2032.
Nvidia is also an investor in CoreWeave. At the start of 2026, Nvidia invested $2 billion in CoreWeave. OpenAI, another investee, also buys CoreWeave compute. To close the loop, OpenAI invested directly in CoreWeave.
The relationships can be mutually beneficial when business is booming. It helps Nvidia set up its own ecosystem in the event that the hyperscalers turn to competing chips. And it’s likely that Nvidia has some kind of revenue sharing agreement, meaning it will participate in the upside beyond the value of its equity. But if demand slows, the financing loop can be problematic. If a major customer cuts its spending with CoreWeave, that could not only hurt the value of Nvidia’s investment but also increase the amount of unused capacity Nvidia would have to buy, subject to the terms of the agreement.
Other arrangements Nvidia has are less clear. In June, SharonAI ($SHAZ), an Australian neocloud provider, announced a six-year compute collaboration with Nvidia, with a stated contract value of up to $4.88 billion. SharonAI’s filing says that it may try to sell the compute to third parties and split the revenues with Nvidia. The filing doesn’t illuminate the details further.
As for the $20 billion in data center leases, it looks like Nvidia signs those upfront and plans to subsequently transfer them to neocloud counterparties. Nvidia describes these leases as roughly 15-year commitments, which are expected to start in fiscal 2028 or 2029 and then be reassigned to third parties. It isn’t clear if that’s supposed to happen before or after the construction is complete.
Consider the data centers that Miami-based Hut 8 ($HUT) — which itself posts huge losses — is building at Beacon Point in Texas. The Financial Times identified Nvidia as the tenant. But the Wall Street Journal reported that Lambda, a privately held cloud computing company backed by Nvidia, has a $35 billion deal to provide computing to Anthropic at the facility. Nvidia will provide the chips. The deal, as the Journal noted, helps Lambda get a contract with Anthropic without needing to lease a data center on its own.
The terms under which Nvidia would share any of Lambda’s revenues aren’t disclosed.
In effect, Nvidia is no longer a chip supplier but rather a credit backstop for data center developers.
WHAT HAPPENS IF A TENANT CAN’T PAY?
Layered on top of that $366 billion is another $108.5 billion, which represents a different way in which Nvidia is supporting data centers. In this case, Nvidia isn’t the tenant. Instead, Nvidia has agreed to cover the shortfall if the tenant defaults.
By far the deal’s largest component — accounting for $105 billion — is tied to SB Energy, a SoftBank portfolio company, and its massive PORTS-Pike Technology Campus in Pike County, Ohio, built for OpenAI. In essence, if OpenAI cannot pay, Nvidia is on the hook for up to $105 billion. Nvidia also has agreed to make a $3 billion investment in SB Energy.
SB Energy was supposed to go public this fall, but postponed its IPO amid pushback about the valuation it wanted and broader questions about data centers. Investors also questioned SB Energy’s reliance on OpenAI. Indeed, what’s striking about this is that OpenAI’s commitment reportedly wasn’t enough. The deal needed Nvidia’s backstop.
That shows the doubt that is increasingly creeping into the ecosystem, and how all roads lead back to Nvidia. If Nvidia is using its credibility to bridge what will turn out to be short-lived shakiness, it’s a smart move. It’ll seem less smart if the temporary wobble turns into a bigger rout.
In a fun additional bit of circularity showing Nvidia isn’t the only one doing it: The tenant at one of SB Energy’s first data center projects, dubbed Cosmos, in Austin, Texas, is an affiliate of SoftBank. SB Energy expects approximately $2.5 billion in rent over the next 15 years.
The data and R&D center will be occupied by Graphcore, an AI chipmaker SoftBank purchased in 2024. Graphcore itself had no product sales revenue as of its latest annual filing for the period ending in March 2025, relying almost entirely on SoftBank for R&D funding.
NVIDIA THE INVESTOR
Another way to think about Nvidia’s commitments is through an entirely separate category, its equity investments. These create loops that aren’t so much circular as they are reflexive and self-reinforcing — at least, until they are not.
Nvidia has equity stakes in the companies it’s doing these deals with. In total, the company has $99 billion in equity investments, which it makes both through its venture capital arm, NVentures, and at the corporate level. The portfolio spans 229 private companies and 13 publicly traded companies. According to a recent 13F SEC filing, the investments include Intel ($INTC), SpaceX ($SPCX), CoreWeave, Coherent ($COHR), Nokia ($NOK), Nebius ($NBIS) and more; across the public and private portfolio, the investments range from data center construction and AI model development to energy supply and hardware manufacturing.
Nvidia’s second-biggest publicly traded stake — behind Intel — is in SpaceX. It owns 122.8 million SpaceX shares, which it acquired by helping to fund xAI, which SpaceX later bought. The stake is worth roughly $17 billion today. On the company’s first earnings call, Musk announced that SpaceX was “exclusive to Nvidia.” SpaceX just raised $40 billion in debt, a large portion of which is earmarked for the purchase of Nvidia’s chips.
The figure also includes Nvidia’s funded investments in OpenAI and Anthropic. The publicly held securities are marked to market quarterly, but the private ones are held at cost and written up when a new funding round sets a higher price.
In the first half of fiscal 2027, Nvidia recorded $23.7 billion in net equity gains, representing almost 17% of pretax income. A downward turn in valuations would of course cut the other way.
While the portfolio looks diversified, it is in reality a concentrated bet on AI. And the companies are usually buyers of Nvidia’s chips. For instance, in October 2024, Poolside, an AI model and software company, announced that it had brought 10,000 Nvidia GPUs online; Nvidia has also helped to fund Poolside. So Nvidia is both an investor and supplier. As is often the case, the size of its investment and the share returned through sales of chips to Poolside aren’t disclosed. So long as Poolside succeeds, Nvidia prospers, but if it fails, Nvidia suffers in two ways: Its equity investment loses money, and its sales to Poolside go away.
The more you dig into it, the more elaborate the relationships are. Nvidia-backed companies may buy chips from Nvidia, but they may also buy computing from neoclouds that Nvidia backs. For instance, Nvidia has invested in AI software companies Mistral and Cohere, both of which use Nvidia’s chips. Both companies also use CoreWeave for compute capacity. So if Mistral or Cohere were to fail, that would hurt Nvidia’s investment and chip sales. But it would also take customers away from CoreWeave, which might put Nvidia on the hook to buy CoreWeave’s capacity, as well as negatively impact the value of the stake Nvidia has in CoreWeave.
All three companies — Poolside, Mistral and Cohere — are private, so it’s difficult to know if they are profitable or not. But assuming they are still dependent on venture capital, that means their health depends on the willingness of investors to continue funding them.
Nvidia’s investments can be hard to track, in part because Nvidia is also investing in the funds that themselves make investments in AI. For instance, Brookfield, the investment manager, identified Nvidia as the $2 billion anchor limited partner in its AI infrastructure fund. It isn’t fully clear what investments that fund has made, or what share Nvidia has of them.
Brookfield also says that Nvidia is a critical supplier to at least one portfolio company.
Separately, Nvidia is also investing $1 billion in a Korean internet company called NAVER whose data center buildout is being partly financed by Brookfield; NAVER is buying Nvidia’s chips. Brookfield’s September Investor Day transcript does not disclose how much of Nvidia’s commitment has been funded or its share of each underlying asset.
Brookfield is also one of the six firms in Nvidia’s announced compute-financing initiative, alongside Apollo, BlackRock, Blackstone, Goldman Sachs and KKR. The group aims to mobilize more than $500 billion in third-party capital for Nvidia-based AI infrastructure. The arrangement is yet another way for Nvidia to make sure that customers can afford to buy its chips without necessarily financing the purchases themselves. One way to read this is an attempt on Nvidia’s part to have other deep-pocketed investors help pay for the Nvidia-based infrastructure that AI companies need. The key question is how much risk outside investors are willing to take, and how much risk Nvidia will have to retain in order to persuade them to participate. Huang said on X that Nvidia could backstop up to $125 billion, or 25%, of the deals. (The initiative is similar to Broadcom’s financing arrangement with Anthropic, which uses Alphabet’s TPUs, in that both aim to help customers access computing capacity while encouraging reliance on a particular chip supplier.)
Nvidia’s relationship with British AI company Nscale provides another example of its overlapping roles. Nvidia has committed $1 billion in convertible loan notes to the company, in which it also apparently has a stake. At Nscale’s Ward County, Texas facility, Nvidia guarantees up to $860.3 million of rent for the first five lease years. The Information recently reported that Nvidia is in talks to potentially provide more than $5 billion in guarantees for another data center Nscale is building (with Nvidia chips, of course) in West Virginia; if Nscale were to default, Nvidia would step in, even though Anthropic has a $45 billion contract with Nscale for this facility.
Nscale’s S-1 filing also lists $24 billion of outstanding commitments to buy equipment for 2026 and 2027; it isn’t clear how much of this is purchases from Nvidia.
Nscale has had to delay its IPO amid investor skepticism. Firmus, the Australian data center firm that has a similar arrangement with in which Nvidia, has had to pull its public listing. The Information has reported that after Firmus’s IPO was pulled, Nvidia and Firmus began discussions for Nvidia to inject several hundred million dollars into it.
The talks could demonstrate Nvidia’s ability to cover a funding gap. Alternatively, they could leave Nvidia with more money invested in companies that outside investors are unwilling to finance.
WHAT HAPPENS WHEN THE CAROUSEL HALTS?
So is Huang right when he says that for every $1 Nvidia invests, $100 is coming back? Unfortunately, there is no way to independently verify that. Nor is it possible to estimate what share of Nvidia’s revenue is dependent on demand that it is funding or protecting.
Unsurprisingly, Nvidia says its exposure is manageable. Chief Financial Officer Colette Kress said on the August earnings call that Nvidia’s “risk is limited” in backing AI labs because it can redeploy its chips to other customers. Nvidia did not return several requests for comment and clarification.
But that’s true only as long as any problems remain isolated, rather than part of a more systemic breakdown.
Ramp economist Ara Kharazian says that 80% of spend on OpenAI and Anthropic is driven by 1% of firms. In an interview with Derek Thompson, Kharazian pointed out that these customers are heavily concentrated in software and technology. It isn’t clear to what extent these customers are being financed by venture capital, or to what extent apparent demand for AI might be demand created by investors betting on AI — and supposedly disparate demand might all be correlated. If those customers need a continued influx of funds to keep spending, then any downturn could cause a lot of demand to evaporate.
On top of that, research firm Gartner has predicted that by 2030, 80% of neoclouds will cease independent operations. And the need for more and more capital means that the boom is in the hands of an increasingly wary — and expensive — bond market.
The hedge fund Orso also warns there may be a massive oversupply of compute, which could be a huge problem for the circular GPU economy. Greener points out that there was a dress rehearsal for this very scenario. In 2017 and 2018, demand for Nvidia chips was skyrocketing, because cryptocurrency miners were grabbing them to mine Ethereum. When that market crashed, demand evaporated, and Nvidia chips reportedly ended up on eBay for resale.
Any one of these scenarios could trigger losses for Nvidia. If neoclouds default, Nvidia loses the chip sales and its investments and is on the hook for some amount of rent payments. If venture capital backed AI companies that are in the top 1% cut back on their AI spending, that harms Nvidia’s investments and chip sales. If demand for its products declines, Nvidia is on the hook for supply commitments it may no longer need. If OpenAI or Anthropic cannot pull off their IPOs, then Nvidia’s investments in those companies are worth less, and they have to raise additional money from the private market in order to make good on their commitments. (OpenAI reportedly has raised less than half the $30 billion it had initially targeted for its latest funding round.) That in turn would likely increase both the draw from Nvidia as an investor and the likelihood that Nvidia will be liable for the various rent guarantees.
And on and on. Each of these is manageable in isolation, and Fitzgerald points out that Nvidia’s fat margins mean that it could still emerge as a highly profitable company in many scenarios. But then again, what looks like linear logic can become chaos theory once the music stops. Or to put it differently, when fear sets in, the outcome stops being predictable.
That said, Nvidia generates massive amounts of cash. From the beginning of fiscal 2027, through the end of fiscal 2028, the company is expected to produce over $500 billion in free cash flow. With that, plus its cash on hand, the company could cover all of its commitments. (And even in a worst-case scenario, those commitments don’t come due right away.) But of course, the commitments are getting bigger rapidly, and some of Nvidia’s money is spoken for.
In the first half of fiscal 2027, the company generated about $70 billion of free cash flow and spent a net $35 billion on investments. If Nvidia’s growth in chip revenues is dependent on its continued investments, then those investment dollars aren’t discretionary. On top of that, Nvidia has authorized a remaining $235 billion to a massive share buyback. If it were to rescind that, its stock would likely fall.
And if Nvidia were to falter, the market would likely crash. Analysts expect companies in the S&P 500 to report a 30% rise in third-quarter earnings from a year ago, but just two companies — Nvidia and Micron — are projected to account for 34% of that growth. Bulls point out that after its 15% slide from its high in early October, Nvidia’s stock is selling for less than 15 times fiscal 2028’s estimated earnings. After the massacre on November 5, the stock arguably is even cheaper.
Whether this is a buying opportunity or a harbinger of problems to come depends on the answer to the great question of our day: Whither the AI boom?
Engage your harness. The vertical loop on this one could be stomach-churning.
AUTHOR
Bethany McLean is the investigative journalist who exposed the notorious Enron fraud while a reporter at Fortune. She is a contributing editor at Vanity Fair who authored The Smartest Guys in the Room and several other books. She began her career as an investment banking analyst at Goldman Sachs before moving into journalism.
EDITORS
Vikas Kumar joined Hunterbrook from The Capitol Forum, where he led the corporate investigations team for a decade as a senior editor. He was previously an attorney at Gordon Feinblatt, a trial attorney for the Department of Justice, and a law clerk for a federal judge. He has a J.D. from University of Virginia School of Law and a bachelor’s from Emory University. Vikas is based in Maryland.
Jim Impoco is the award-winning former editor-in-chief of Newsweek who returned the publication to print in 2014. Before that, he was executive editor at Thomson Reuters Digital, Sunday Business Editor at The New York Times, and Assistant Managing Editor at Fortune. Jim, who started his journalism career as a Tokyo-based reporter for The Associated Press and U.S. News & World Report, has a Master’s in Chinese and Japanese History from the University of California at Berkeley.
GRAPHICS
Dan DeLorenzo is a creative director with 25 years reporting news through visuals. Since first joining a newsroom graphics department in 2001, he has built teams at Bloomberg News, Bridgewater Associates, and the United Nations, and published groundbreaking visual journalism at The Wall Street Journal, Associated Press, The New York Times, and Business Insider. A passion for the craft has landed him at the helm of newsroom teams, on the ground in humanitarian emergencies, and at the epicenter of the world’s largest hedge fund. He runs DGFX Studio, a creative agency serving top organizations in media, finance, and civil society with data visualization, cartography, and strategic visual intelligence. He moonlights as a professional sailor working toward a USCG captain’s license and is a certified Pilates instructor.
DISCLOSURES
© 2026 Hunterbrook Media LLC. All rights reserved. Use of this website is strictly governed by our Terms of Use. The content herein is furnished on an “AS IS” basis without any form of express or implied warranty. For information regarding our privacy practices, please refer to our Privacy Policy.
Hunterbrook Media LLC (”Hunterbrook Media”) is an investigative news organization. Hunterbrook Media is affiliated with Hunterbrook Capital LP (”Hunterbrook Capital”), an exempt reporting adviser with the U.S. Securities and Exchange Commission that serves as investment adviser to one or more investment funds. Hunterbrook Media and Hunterbrook Capital are legally separate entities under common control. Hunterbrook Capital’s investment activities are one source of funding for Hunterbrook Media’s journalistic operations. Hunterbrook Capital may hold long positions, short positions, positions through derivative instruments including options and swaps, or no position in any security covered or mentioned on this website. Consistent with applicable policies and procedures, Hunterbrook Capital may establish, modify, or close positions in covered securities before or after the publication of any Hunterbrook Media article. Following publication of any article, Hunterbrook Capital will continue transacting in covered securities for an indefinite period and may be long, short, or flat at any time thereafter, regardless of any position described at publication. Hunterbrook Media has no obligation to update any article or disclosure to reflect subsequent changes in Hunterbrook Capital’s positions.
Nothing on this website constitutes investment advice, a recommendation to buy, hold, or sell any security, or a solicitation to purchase or sell any securities. No securities shall be offered or sold in any jurisdiction where such activities would be contrary to applicable securities laws. Hunterbrook Media is not a registered investment adviser in the United States or any other jurisdiction. Nothing herein should be construed as investment advice or a recommendation of any kind. This information should not be relied upon as a substitute for independent research or professional financial, legal, or tax advice.
This website may feature forward-looking statements reflecting Hunterbrook Media’s current views. Such statements, identifiable by terms including but not limited to “anticipate,” “believe,” “estimate,” “expect,” “intend,” “may,” “plan,” “predict,” “should,” and “will,” are inherently speculative and subject to risks and uncertainties. Actual results or outcomes may substantially deviate from those projected. Hunterbrook Media expressly disclaims any obligation to update or revise any forward-looking statements, regardless of subsequent developments or new information.
The information presented is current as of the date indicated. No representation regarding the completeness or timeliness of this information is made. Some information is sourced from third parties and, while believed to be reliable, has not been independently verified, and its accuracy or completeness is not guaranteed. Hunterbrook Media is not affiliated with any sites linked to this website. Investment in securities and other financial instruments involves significant risk, including the potential loss of principal. Users are advised to conduct their own due diligence and consult professional advisors before engaging in any investment activity. Use of Hunterbrook Media’s content is entirely at the user’s risk. Users shall not use this site for any illegal or prohibited purposes and shall comply with all applicable local, state, national, and international laws and regulations.
Should any provision of these Terms of Use be adjudged invalid or unenforceable, the remaining provisions shall remain in full force and effect. Trademarks contained in links to third-party websites belong to their respective owners. Hunterbrook Media retains copyright on all text, content, graphics, and trademarks displayed on this site.